Key Takeaway
The RBI's latest assessment underscores India's formidable economic resilience, positioning the nation as a compelling investment destination amidst global headwinds. Investors should prioritize sectors poised for domestic growth, infrastructure, and financial services, while carefully navigating inflation risks from crude oil.
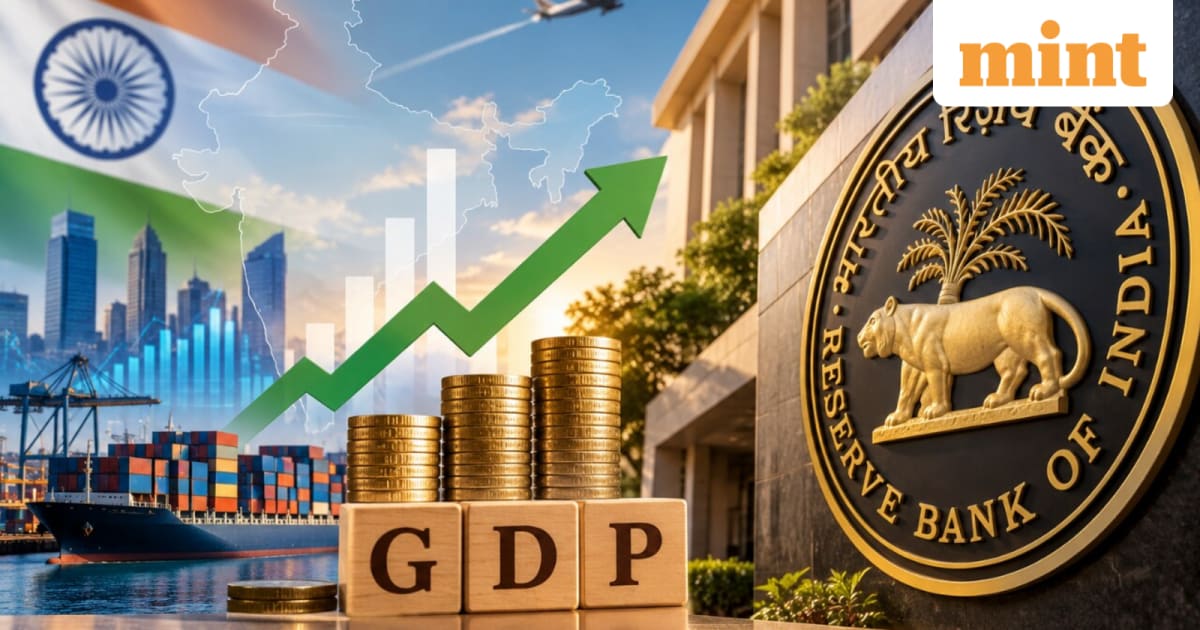
The Reserve Bank of India (RBI) has issued a resounding vote of confidence in India's economic resilience, highlighting its robust financial and external sectors despite escalating global risks and geopolitical tensions. This positive outlook could significantly bolster investor confidence, attracting increased foreign institutional investments (FIIs) into Indian equities and strengthening the Rupee. Our deep dive analyzes the profound market implications, identifying key winners and potential pitfalls for your portfolio.
India's Economic Fortress: Unpacking the RBI's Resilience Report and its Stock Market Implications
The Reserve Bank of India (RBI) recently delivered a powerful affirmation of India's economic fortitude, declaring the nation's financial and external sectors to be remarkably resilient in the face of persistent global risks and escalating geopolitical tensions. This isn't just a routine bulletin; it's a strategic pronouncement that reverberates across global financial corridors, signalling India's growing stature as a safe haven and growth engine amidst a fragmented world economy. For investors, this assessment is far more than mere rhetoric; it’s a critical signpost for capital allocation, pointing towards sustained domestic demand, robust corporate earnings, and a potentially stabilizing Rupee.
The context for this resilience is crucial. Global growth forecasts remain subdued, inflation battles persist in developed economies, and the spectre of West Asian conflicts casts a long shadow over energy markets. Yet, India stands out, buoyed by strong domestic consumption, robust capital expenditure, and a burgeoning digital economy. This confluence of factors creates a compelling narrative for long-term investors, particularly those seeking diversification away from more volatile developed markets. The RBI's positive assessment effectively de-risks a significant portion of the Indian growth story, making it a prime candidate for enhanced FII inflows, which have historically been a major driver for benchmark indices like the Nifty 50 and BSE Sensex.
How Will India's Economic Resilience Impact the Stock Market?
The RBI's optimistic stance translates directly into a bullish sentiment for the Indian equity market, offering a strong fundamental underpinning that could propel valuations higher. A resilient economy implies stable corporate earnings, robust credit growth, and continued government support for infrastructure, all of which are catalysts for stock performance. Historically, periods of strong domestic economic fundamentals, even amidst global turbulence, have seen the Nifty 50 deliver compounded annual growth rates (CAGR) exceeding 12-15%. For instance, during the post-COVID recovery phase in 2021-2022, when global supply chains were disrupted, India's domestic-led recovery helped the Nifty 50 gain over 24% in 2021, showcasing its decoupling potential.
Sectoral Tailwinds: The most direct beneficiaries are sectors intrinsically linked to domestic growth and capital expenditure. Banking & Financial Services will thrive on increased credit demand, improved asset quality, and higher fee income. With India's credit growth consistently hovering around 15-16% year-on-year, major lenders are poised for significant earnings expansion. Infrastructure and Manufacturing (especially those catering to domestic demand) will benefit from government spending thrusts and capacity utilization improvements. The government's ambitious capex targets, exceeding INR 10 lakh crore for FY24, provide a clear roadmap for growth in these sectors. Furthermore, Services Exports, particularly IT and BPO, are expected to maintain momentum due to global demand for digital transformation, even as global growth faces headwinds.
FII Inflow Dynamics: A key indicator of confidence, FII inflows often follow such strong macroeconomic signals. A robust economic outlook, coupled with a relatively stable Rupee (strengthened by healthy forex reserves nearing $600 billion), makes Indian assets more attractive. When FIIs pour into the market, it typically creates a broad-based rally, often starting with large-cap bellwethers before trickling down to mid-cap and small-cap segments. The last major surge in FII inflows in 2020-21 saw the Nifty 50 add over 40% in just 18 months, highlighting the power of foreign capital.
Key Indian Stocks Poised for Impact from RBI's Positive Outlook
Given the strong underlying economic fundamentals, several bellwether stocks across key sectors are particularly well-positioned to benefit from the RBI's positive assessment. Investors looking to capitalize on India's resilience should consider these names:
- HDFC Bank (NSE: HDFCBANK): As India's largest private sector bank by market capitalization (approx. INR 12.5 trillion), HDFC Bank is a direct proxy for India's financial sector growth. Its robust loan book, healthy asset quality, and extensive distribution network position it to capture significant credit demand from both retail and corporate segments. A resilient economy means lower non-performing assets (NPAs) and higher loan growth, directly boosting HDFC Bank's net interest income (NII). With a P/E ratio typically in the low 20s, it offers a compelling blend of growth and stability. Sector peers like ICICI Bank (NSE: ICICIBANK) and Axis Bank (NSE: AXISBANK) will also see similar tailwinds, albeit with slightly different risk-reward profiles.
- Larsen & Toubro (NSE: LT): A conglomerate with a significant footprint in infrastructure, engineering, and construction, L&T (market cap ~INR 5 trillion) is a direct beneficiary of India's capital expenditure push. Government spending on roads, railways, ports, and green energy projects will translate into a robust order book for L&T. The company's strong execution capabilities and diversified business model make it a cornerstone investment for India's growth story. Its Q2 FY24 order inflows surged by 45%, underscoring the accelerating capex cycle.
- Reliance Industries (NSE: RELIANCE): While Reliance (market cap ~INR 19 trillion) is often viewed through the lens of crude oil, its diversified empire, encompassing retail (Reliance Retail), telecom (Jio Platforms), and new energy ventures, makes it a significant beneficiary of domestic consumption and digital transformation. A strong Indian economy boosts consumer spending, directly impacting Reliance Retail's revenues, while continued data consumption fuels Jio's growth. The crude oil segment presents a mixed picture: higher prices boost upstream earnings but can squeeze refining margins if not passed on. However, the sheer scale and diversification of Reliance provide a strong buffer.
- Tata Consultancy Services (NSE: TCS): As India's largest IT services exporter (market cap ~INR 14 trillion), TCS benefits from global digital transformation trends, but a resilient Indian economy also contributes to its domestic business and strengthens the Rupee, which can impact its reported dollar revenues. While global slowdowns are a risk, the long-term demand for IT services remains intact. A strong Indian macroeconomic environment indirectly supports talent retention and operational stability for these large employers. Peers like Infosys (NSE: INFY) and Wipro (NSE: WIPRO) operate under similar dynamics.
Bulls vs. Bears: Contrasting Views on India's Economic Trajectory
While the RBI's bulletin paints a largely optimistic picture, a balanced perspective requires acknowledging both bullish and bearish arguments.
The Bulls argue: India's structural reforms, demographic dividend, and increasing formalization of the economy provide a multi-year growth runway that is increasingly decoupled from short-term global fluctuations. They point to robust GST collections, surging manufacturing PMI, and strong auto sales as evidence of underlying economic momentum. The government's consistent focus on infrastructure development and 'Make in India' initiatives further strengthens the domestic demand story. From a valuation perspective, while the Nifty 50 trades at a forward P/E of around 20-22x, this is justified by its superior earnings growth trajectory compared to global peers. They would highlight the recent record-breaking FDI inflows, which reached nearly $85 billion in FY22, as a testament to global confidence in India's long-term potential.
The Bears, however, caution: The current resilience might be tested by external shocks, particularly a sustained surge in crude oil prices above $90-100 per barrel due to escalating West Asian conflicts. Such a scenario would fuel domestic inflation, potentially forcing the RBI to maintain higher interest rates for longer, thereby dampening credit growth and investment. Furthermore, despite current resilience, a significant global economic slowdown could eventually impact India's export growth, which currently accounts for roughly 20% of its GDP. They might also point to pockets of consumption slowdown in certain discretionary categories and the persistent challenge of job creation as areas of concern, suggesting that the broad-based recovery may not be as uniform as implied. Additionally, the premium valuations of Indian equities, relative to their historical averages, leave less room for error.
Actionable Investor Playbook: Navigating India's Resilient Growth Story
For investors seeking to capitalize on India's robust economic resilience, a strategic approach is key. The current environment calls for a focus on quality, domestic-oriented growth, and a tactical hedge against potential external shocks.
What to Buy:
- Core Holdings: Establish or increase positions in high-quality large-cap financial services (e.g., HDFC Bank, ICICI Bank) and infrastructure players (e.g., L&T, UltraTech Cement - NSE: ULTRACEMCO). These are direct beneficiaries of India's growth trajectory. Consider entry points during minor market corrections, aiming for P/E ratios slightly below their 5-year averages.
- Growth Opportunities: Look at manufacturing companies with a strong domestic focus (e.g., Maruti Suzuki - NSE: MARUTI, Tata Motors - NSE: TATAMOTORS) and select capital goods manufacturers benefiting from the 'Make in India' push.
- Long-Term Themes: Invest in companies aligned with India's digital transformation and green energy transition (e.g., Tata Power - NSE: TATAPOWER, renewable energy ETFs).
What to Watch/Hold:
- IT Services: Hold positions in large-cap IT services companies (TCS, Infosys) but monitor global economic sentiment closely. While resilient, a severe global recession could impact new deal wins.
- Discretionary Consumption: Keep an eye on FMCG (e.g., Hindustan Unilever - NSE: HINDUNILVR) and consumer durables. While domestic demand is strong, persistent inflation could squeeze margins or impact discretionary spending.
What to Avoid/Reduce Exposure:
- Import-heavy industries: Companies with significant import dependencies (especially raw materials) may face higher input costs if the Rupee depreciates significantly due to external shocks or if global commodity prices spike.
- Highly leveraged companies: In a scenario where interest rates remain elevated, highly indebted companies could face increased financing costs, impacting profitability.
Time Horizon: The resilience narrative is a long-term structural theme. Investors should adopt a 3-5 year horizon to fully realize the potential gains from India's economic trajectory.
Risk Matrix: Navigating Potential Headwinds for Indian Equities
While the outlook is largely positive, prudent investors must be aware of the inherent risks that could temper India's growth story. Our risk matrix assesses the probability and potential impact of key headwinds:
-
Escalating West Asian Conflicts and Sustained High Crude Oil Prices:
- Probability: Medium-High
- Impact: High. A sustained rise in crude oil prices above $90-100 per barrel directly fuels domestic inflation, increases India's import bill, and could lead to Rupee depreciation. This would pressure corporate margins, reduce consumer purchasing power, and potentially force the RBI to maintain higher interest rates, dampening credit growth and investment. Oil Marketing Companies (OMCs) like Indian Oil Corporation (NSE: IOC) and Bharat Petroleum Corporation (NSE: BPCL) would face margin pressure if price hikes are not fully passed on.
-
Significant Global Economic Slowdown/Recession:
- Probability: Medium
- Impact: Medium. While India's domestic-led growth provides a buffer, a severe global recession would inevitably impact India's export-oriented sectors (e.g., IT, textiles, gems & jewellery) and could also dampen FII inflows. This would slow overall GDP growth, even if the domestic engine remains strong.
-
Domestic Inflationary Pressures Beyond Crude:
- Probability: Medium
- Impact: Medium. Beyond crude, unexpected supply-side shocks (e.g., adverse weather impacting food prices) or persistent core inflation could lead to the RBI maintaining a hawkish stance. This would keep borrowing costs high, affecting interest-sensitive sectors like real estate and auto.
-
Unexpected Policy Missteps or Geopolitical Shocks (Non-Crude Related):
- Probability: Low-Medium
- Impact: High. Any significant shift in government policy or unforeseen geopolitical events (e.g., border tensions, trade wars) could temporarily erode investor confidence and trigger market volatility.
What to Watch Next: Catalysts and Data Points for India's Growth Story
The narrative of India's economic resilience is dynamic, shaped by a continuous stream of data and events. Investors should closely monitor the following to stay ahead of market movements:
- RBI Monetary Policy Meetings: The next scheduled meeting is in early December. Any commentary on inflation trajectory, growth forecasts, and interest rate outlook will be crucial for financial markets.
- Inflation Data (CPI & WPI): Monthly Consumer Price Index (CPI) and Wholesale Price Index (WPI) releases are critical indicators of domestic inflationary pressures. Sustained drops towards the RBI's comfort zone (2-6%) could signal potential for future rate cuts, benefiting credit growth.
- Industrial Production (IIP) & Manufacturing PMI: These monthly releases provide a real-time pulse on India's industrial activity and manufacturing health, directly impacting infrastructure and manufacturing sector stocks.
- Quarterly Corporate Earnings: Upcoming Q3 FY24 earnings announcements will provide concrete evidence of how the resilient economy is translating into corporate profitability. Pay close attention to commentary from management on demand outlook and input costs.
- Government Budget (February 2024): The Union Budget is a major policy event that outlines the government's fiscal roadmap, capital expenditure plans, and tax policies, all of which have significant market implications.
- Global Crude Oil Prices: Continuous monitoring of Brent crude oil prices will be essential, given its direct link to India's inflation and current account deficit.
- FII and DII Flow Data: Daily and monthly data on Foreign Institutional Investor (FII) and Domestic Institutional Investor (DII) flows provide insights into investor sentiment and capital allocation trends.
In conclusion, the RBI's unequivocal endorsement of India's economic resilience presents a compelling investment thesis. While global headwinds persist, India's strong domestic fundamentals, robust financial system, and strategic policy interventions position it as a beacon of growth. Astute investors who align their portfolios with these structural strengths, while carefully navigating the identified risks, are well-placed to capture significant value in the coming years.
See HDFC Bank's AI Score
Our algorithmic screener scores HDFC Bank on fundamentals, momentum, and risk — free to try, no card needed.
Try the AI Screener →Have questions about this story?
Ask Welth, our finance-focused AI research assistant, for a deeper breakdown — free trial included.
Chat with Welth AI →Disclaimer: This content is generated by WelthWest Research Desk based on publicly available reports and is for informational purposes only. It does not constitute financial advice, investment recommendations, or an offer to buy or sell securities. Always consult a qualified financial advisor before making investment decisions.