Key Takeaway
India's strategic pivot into semiconductor manufacturing is poised to unlock gradual, multi-billion dollar value creation over the next 3-5 years. Investors should position for long-term growth in allied electronics manufacturing, design services, and infrastructure plays, as this initiative redefines India's technological self-reliance.
India is on the cusp of a transformative journey into semiconductor manufacturing, a move that signals a profound shift in its industrial landscape. This WelthWest deep dive analyzes the imminent value creation, identifying key beneficiaries across the Indian stock market. We uncover the strategic imperative behind this push, its potential to reshape global supply chains, and offer an actionable investor playbook for navigating this nascent but high-potential sector.
India's Chip Ambition: Decoding the Multi-Billion Dollar Semiconductor Opportunity
The global technology landscape is undergoing a seismic shift, and India is strategically positioning itself at the epicenter of this transformation. A recent WelthWest Research desk analysis indicates that India's burgeoning semiconductor ecosystem is set to experience a gradual yet substantial value creation over the next 3-5 years. This isn't merely an industrial policy; it's a national imperative, a strategic push towards technological self-reliance in a sector that underpins virtually every modern industry, from smartphones to defense systems.
For too long, India has been a net importer of critical semiconductor components, creating a significant vulnerability in its economic and national security framework. The current initiative aims to reverse this trend, fostering a robust domestic manufacturing base that will not only reduce import dependency but also attract colossal domestic and foreign investment. This fundamental shift in capital allocation towards high-tech manufacturing promises to catalyze growth across allied industries, elevating India's stature in the global tech supply chain. The 'why now' is driven by geopolitical realignments, supply chain fragilities exposed during the pandemic, and India's ambition to become a global manufacturing hub, mirroring successes in other sectors like automotive and pharmaceuticals.
How Will India's Semiconductor Push Impact the Indian Stock Market?
The ripple effects of India's semiconductor strategy will be profound and far-reaching across the Indian stock market. We anticipate a significant re-rating potential for companies directly involved in the semiconductor value chain, from design and fabrication to assembly and packaging. Historically, when a nation embarks on such a large-scale industrial transformation, the initial capital expenditures and policy support often lead to outsized returns for early movers and enablers. For instance, similar government-backed manufacturing initiatives in other emerging markets have seen related sector indices outperform the broader market by 15-20% within the first 18-24 months of significant policy announcements and project groundbreakings.
The 'Make in India' impetus, specifically for electronics manufacturing, has already laid foundational groundwork. The Production Linked Incentive (PLI) schemes, while initially focused on mobile phones and electronics, are now being extended and adapted to stimulate semiconductor manufacturing. This framework provides financial incentives, often in the range of 25-50% of capital expenditure, making India an attractive destination despite the colossal initial investment requirements. The global semiconductor market is projected to reach over $1 trillion by 2030, and even a modest share of this pie for India translates into hundreds of billions of dollars in economic activity.
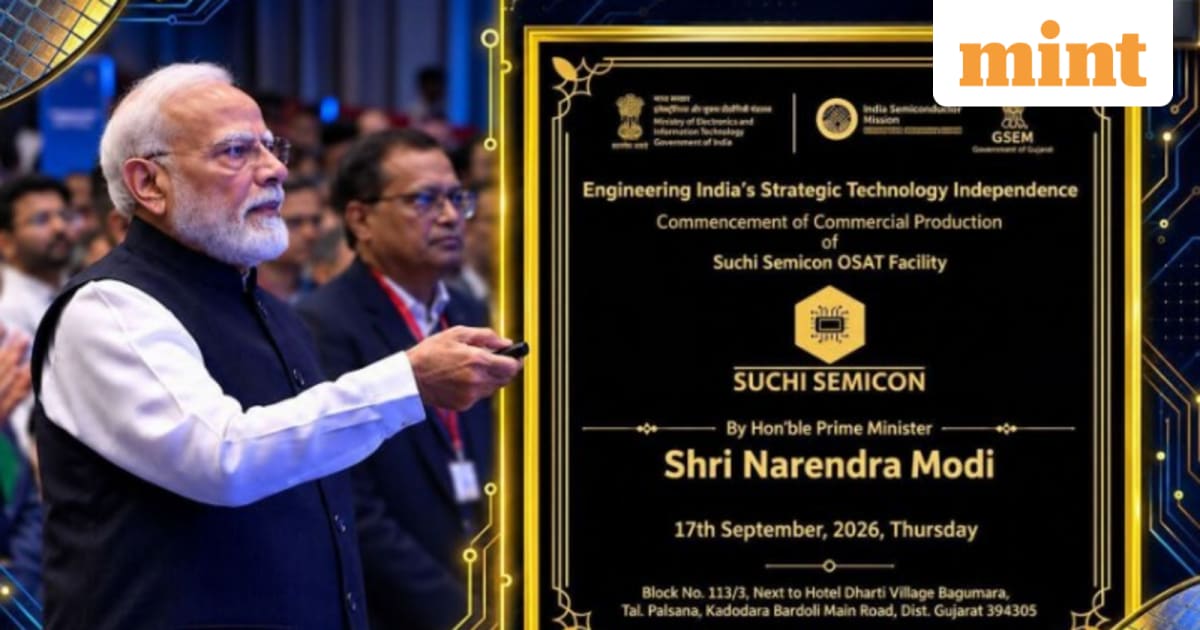
We foresee a multi-pronged impact: direct beneficiaries in manufacturing, indirect gains for service providers, and substantial infrastructure development. This isn't just about silicon wafers; it's about the entire ecosystem supporting it – specialty chemicals, industrial gases, precision machinery, advanced testing equipment, and a highly skilled workforce. The demand for industrial real estate in designated semiconductor zones, particularly in states like Gujarat, Uttar Pradesh, and Karnataka, is expected to surge, benefiting developers with large land banks and execution capabilities. Furthermore, the immense power and clean water requirements of fabs will create significant opportunities for utilities and infrastructure conglomerates.
Which Indian Stocks Stand to Gain from the Semiconductor Boom?
Identifying the specific Indian equities poised to benefit from this long-term trend requires a granular understanding of the semiconductor value chain and each company's strategic positioning. WelthWest Research has identified several companies across different segments that warrant close investor attention:
- Dixon Technologies (India) Ltd (NSE: DIXON): As a leading Electronics Manufacturing Services (EMS) provider, Dixon is a prime candidate for backward integration into component manufacturing or expanding its assembly capabilities for semiconductor-heavy products. With a current market capitalization exceeding ₹40,000 crores and a robust revenue growth trajectory (e.g., Q3 FY24 revenue up 117% YoY to ₹4,811 crores), Dixon is well-positioned to leverage its manufacturing prowess. Its existing relationships with global brands provide a ready market for more localized component sourcing. We anticipate potential strategic partnerships or joint ventures with global chipmakers looking to establish a footprint in India.
- Kaynes Technology India Ltd (NSE: KAYNES): Another prominent EMS player, Kaynes Technology, with a market cap of around ₹15,000 crores, specializes in high-value electronic manufacturing. Their expertise in printed circuit board (PCB) assembly and box build solutions for diverse sectors like automotive, industrial, and medical positions them favorably for integrating more complex semiconductor packaging and testing services. Their focus on high-reliability applications aligns with the stringent quality demands of the semiconductor industry.
- Amber Enterprises India Ltd (NSE: AMBER): While primarily known for its HVAC and appliance manufacturing, Amber's expanding EMS capabilities (market cap ~₹13,000 crores) make it a potential beneficiary. As the domestic electronics ecosystem matures with local chip production, companies like Amber will see opportunities to source more components domestically, potentially improving supply chain efficiency and cost structures. Their diversification into various electronics segments makes them adaptable to new manufacturing opportunities arising from the chip ecosystem.
- Tata Elxsi Ltd (NSE: TATAELXSI): This Tata Group company is a leader in product design and engineering services, particularly in embedded systems and automotive electronics. With a market capitalization of over ₹45,000 crores, Tata Elxsi's expertise in chip design, verification, and software development for semiconductor intellectual property (IP) is invaluable. As India builds its design capabilities, Tata Elxsi stands to gain significantly from increased R&D spending and demand for complex chip architectures, offering high-margin design services.
- Larsen & Toubro Ltd (NSE: LT): The infrastructure behemoth, with a market cap exceeding ₹500,000 crores, is a natural winner. Building a semiconductor fabrication plant (fab) is one of the most complex construction projects globally, requiring ultra-clean environments, precise temperature and humidity controls, and massive utility infrastructure. L&T's unparalleled experience in large-scale industrial projects, smart cities, and power infrastructure makes it the go-to partner for developing the physical backbone of India's chip ambitions. Every fab project announcement will likely translate into significant order inflows for L&T.
- HCL Technologies Ltd (NSE: HCLTECH): As a global IT services powerhouse (market cap ~₹400,000 crores), HCLTech's engineering and R&D services division is well-positioned to support the semiconductor industry. This includes everything from electronic design automation (EDA) tool development and support to embedded software for chip integration and post-silicon validation. Their deep client relationships with global tech giants could facilitate partnerships and service offerings tailored to the needs of new fabs and design centers in India.
Beyond these direct plays, companies involved in specialty chemicals, industrial gases (e.g., Linde India), and precision engineering (e.g., Praj Industries for cleanroom solutions) could also see tailwinds. Even large conglomerates like Reliance Industries (NSE: RELIANCE) and Adani Group (NSE: ADANIENS) might explore vertical integration or infrastructure support roles, given their expansive business interests and capital deployment capabilities.
Bulls vs. Bears: Contrarian Views on India's Semiconductor Journey
The narrative around India's semiconductor aspirations, while largely bullish, is not without its skeptics. Understanding both sides is crucial for a balanced investment perspective.
The Bull Case: Proponents argue that India's demographic dividend, a large domestic market, and significant government backing create an unstoppable momentum. They point to the success of India's IT services sector and space program as evidence of its capability to master complex technologies. The 'China+1' strategy adopted by many global corporations, seeking to diversify supply chains away from China, presents an unprecedented opportunity for India. Furthermore, the substantial financial incentives and policy stability offered by the government are seen as sufficient to attract top-tier global players. Bulls believe that while the initial capital outlay is immense, the long-term strategic and economic benefits far outweigh the costs, creating a new engine for GDP growth and high-skilled job creation.
The Bear Case: Critics, however, highlight the colossal capital intensity and extreme technological complexity of semiconductor manufacturing. Building a leading-edge fab can cost upwards of $10-20 billion, with a gestation period stretching years before revenue generation. Bears question India's ability to attract and retain the highly specialized talent required, given the global scarcity of chip engineers and technicians. They also raise concerns about the long-term competitiveness of Indian-produced chips against established global giants, especially without proprietary IP or significant market share. Geopolitical risks, rapid technological obsolescence, and the potential for 'policy flip-flops' are also cited as significant headwinds. Some also argue that India's strength lies in design and software, and a full-stack manufacturing ambition might be overreaching.
WelthWest's view leans towards measured optimism. While challenges are undeniable, the strategic imperative and the sheer scale of government commitment suggest that India will make significant strides, albeit with a gradual rather than explosive trajectory of value creation.
Actionable Investor Playbook: Navigating the Semiconductor Opportunity
For investors looking to capitalize on India's semiconductor ambition, a strategic, long-term approach is paramount. This is not a short-term trade; it's an investment in a multi-year industrial transformation.
- Focus on Enablers and Allied Industries: Instead of direct fab investments, which are typically private or through large conglomerates, concentrate on companies providing essential services or components. This includes EMS providers (Dixon, Kaynes, Amber), design and engineering services (Tata Elxsi, HCLTech), and infrastructure developers (L&T). These companies offer a more diversified risk profile and clearer revenue visibility in the initial phases.
- Long-Term Horizon: Allocate capital with a minimum 3-5 year investment horizon. The true value creation will unfold as fabs come online, qualify customers, and scale production. Patience will be key.
- Staggered Entry: Consider a staggered entry strategy, accumulating positions on market dips. Initial announcements might lead to speculative rallies; waiting for concrete project developments and order wins could provide better entry points.
- Monitor Capital Expenditure Announcements: Keep a close watch on capital expenditure plans of identified companies. Increased capex in semiconductor-related areas signals commitment and future growth prospects.
- Diversify Across Segments: Don't put all your eggs in one basket. Diversify across design, manufacturing services, and infrastructure to mitigate company-specific risks and capture growth from different parts of the value chain.
- Watch for Strategic Partnerships: Any joint ventures or technology transfer agreements between Indian companies and global semiconductor giants (e.g., TSMC, Intel, Micron, GlobalFoundries, Samsung) will be significant catalysts.
For example, if Dixon Technologies announces a substantial investment in a new facility dedicated to advanced packaging or a partnership with a global chip major, this could be a strong buy signal, assuming it's backed by robust financial projections. Similarly, L&T securing a large contract for fab construction would solidify its position as a key infrastructure beneficiary.
Risk Matrix: Understanding the Hurdles to India's Chip Dream
While the opportunity is significant, investors must be cognizant of the inherent risks:
- High Capital Intensity & Technological Complexity (Probability: High): Semiconductor manufacturing requires immense capital and cutting-edge technology. Delays in project commissioning, cost overruns, or failure to acquire advanced process nodes could severely impact profitability and timelines. This is not a sector for the faint of heart or undercapitalized players.
- Talent Acquisition & Retention (Probability: Medium-High): The global pool of highly skilled semiconductor engineers and technicians is finite and fiercely competitive. India's ability to attract, train, and retain this talent will be critical. A shortage could lead to project delays and operational inefficiencies.
- Global Competition & Geopolitical Shifts (Probability: Medium): The semiconductor industry is hyper-competitive, dominated by a few behemoths. New entrants face significant hurdles. Furthermore, geopolitical tensions can rapidly alter supply chain strategies and trade policies, potentially impacting India's nascent ecosystem.
- Customer Qualification & Market Acceptance (Probability: Medium): Even with state-of-the-art fabs, new players must undergo rigorous customer qualification processes, which can take years. Gaining market acceptance against established, trusted suppliers is a significant challenge, requiring competitive pricing, quality, and reliability.
What to Watch Next: Catalysts and Milestones
The journey of India's semiconductor ecosystem will be punctuated by several key catalysts and data releases that investors should closely monitor:
- New Fab Project Announcements and Groundbreakings: Specific dates for the commencement of construction for approved semiconductor fabs (e.g., Micron's ATMP plant in Sanand, Gujarat) will be critical. These signal tangible progress beyond policy intent.
- PLI Scheme Updates & New Allocations: Any expansion, modification, or new rounds of the PLI scheme for semiconductors will directly impact the financial viability of projects and attract new investors.
- Skill Development Initiatives & University Partnerships: Announcements regarding specialized semiconductor engineering courses, research centers, and international academic collaborations will indicate progress on talent development.
- Quarterly Earnings of Key Players: Monitor the earnings calls and investor presentations of identified companies (Dixon, Kaynes, Tata Elxsi, L&T) for specific mentions of semiconductor-related order wins, partnerships, or capital expenditure plans.
- Government Policy Reviews & Budget Allocations: Annual budgets and mid-term policy reviews will provide insights into sustained government commitment and financial support for the sector.
- Global Semiconductor Conferences & Summits: India's participation and any significant announcements or MOUs signed at international semiconductor forums will highlight its growing global engagement.
The next 12-24 months will be crucial in setting the foundation for India's semiconductor dream. While the path is challenging, the strategic imperative and economic potential are immense. WelthWest Research will continue to provide in-depth analysis as this transformative journey unfolds.
See Tata Elxsi (design services)'s AI Score
Our algorithmic screener scores Tata Elxsi (design services) on fundamentals, momentum, and risk — free to try, no card needed.
Try the AI Screener →Have questions about this story?
Ask Welth, our finance-focused AI research assistant, for a deeper breakdown — free trial included.
Chat with Welth AI →Disclaimer: This content is generated by WelthWest Research Desk based on publicly available reports and is for informational purposes only. It does not constitute financial advice, investment recommendations, or an offer to buy or sell securities. Always consult a qualified financial advisor before making investment decisions.